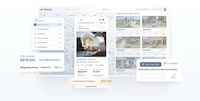
Zillow Home Loans is expanding access to homeownership through forgivable home down payment loans that help eligible FHA borrowers purchase properties without saving the full minimum down payment. The program provides up to 3.5% of a home's purchase price or appraised value, whichever is lower, through a separate loan carrying no interest or monthly payments.
Available in 43 states and Washington, D.C., the assistance is forgiven after five years of timely mortgage payments and continued owner occupancy. Applicants need a minimum 640 credit score, but there are no income limits or first-time buyer requirements. Early refinancing, selling, or moving triggers repayment of the assistance.
For Zillow, combining mortgage financing and down payment support creates opportunities to serve buyers facing upfront affordability challenges. The arrangement also simplifies access to financial assistance by allowing qualified customers to manage both through Zillow Home Loans.
Image Credit: Zillow Home Loans
What's Driving This Trend
- Forgivable Financing
- Zero-interest, deferred-payment loan structures are reshaping affordability models by turning upfront cost barriers into retention-based financial products.
- Integrated Homebuying Platforms
- Combining search, mortgage origination, and buyer assistance within one ecosystem creates room for platforms to capture more of the real estate transaction journey.
- Occupancy-based Incentives
- Forgiveness tied to timely payments and owner occupancy introduces new ways to align borrower behavior, lender risk, and housing stability outcomes.
Who This Affects Most
- Real Estate
- Digital housing marketplaces are positioned to expand beyond listings by embedding financing tools that address affordability gaps earlier in the purchase process.
- Mortgage Lending
- Alternative down payment assistance models create competitive differentiation for lenders serving qualified borrowers with limited cash savings.
- Financial Technology
- Fintech-enabled loan administration can streamline eligibility, repayment triggers, and forgiveness tracking across complex consumer financing programs.